AI shifts CFO time from reconciliation to exception-based decision making.
Key takeaways

Start with repeatable prompts; scale successes into skills, workflows and agents.
Measure AI success by decision quality, not time saved.
The last thing a private fund chief financial officer needs is another abstract lesson on AI. Instead, they need a practical view of how AI can reduce time spent on routine fund finance work and create more capacity for judgment, oversight and decisions.
Over the past 18 months and more than 20 roundtables, seminars, webinars and workshops involving over 700 CFOs and fund controllers, RSM has heard a consistent story: AI adoption is real, but foundational at many firms. Leaders remain concerned about governance, data readiness and employee adoption, and how AI fits into daily workflows when data quality, permissions, confidentiality and human review matter.
As investment activity, investor expectations and reporting requirements increase, the burden on accounting and finance teams grows. When finance operations cannot scale at the same pace, the back office can become a constraint on growth and the limited partner (LP) experience.
Turning routine work into repeatable instructions
The firms that are winning with AI are not the ones out-innovating everyone else. They are out-executing on the fundamentals, shifting time from gathering and reconciling information to analyzing, advising and deciding, and focused on return on investment, not just speed.
They can use approved tools, like Microsoft, to apply well-engineered prompts to recurring tasks to sort through information, summarize documents, analyze data and produce higher-caliber outputs. The benefit goes beyond efficiency. Paired with source materials and human review, AI can help surface exceptions, unsupported assertions, missing approvals and governance gaps buried in documents, workflows or reconciliations. As CFOs refine what works, successful prompts can evolve into repeatable AI skills and building blocks for AI agents and integrated workflows.
Not every use case requires the same level of enablement. Some begin with an approved AI assistant; others require standardized prompts, curated source materials and defined review protocols. The usefulness of the output improves meaningfully when prompts are grounded in governing documents, such as policies, side letters and investor records. More advanced use cases connect AI to governed data, workflow, approval and monitoring capabilities.
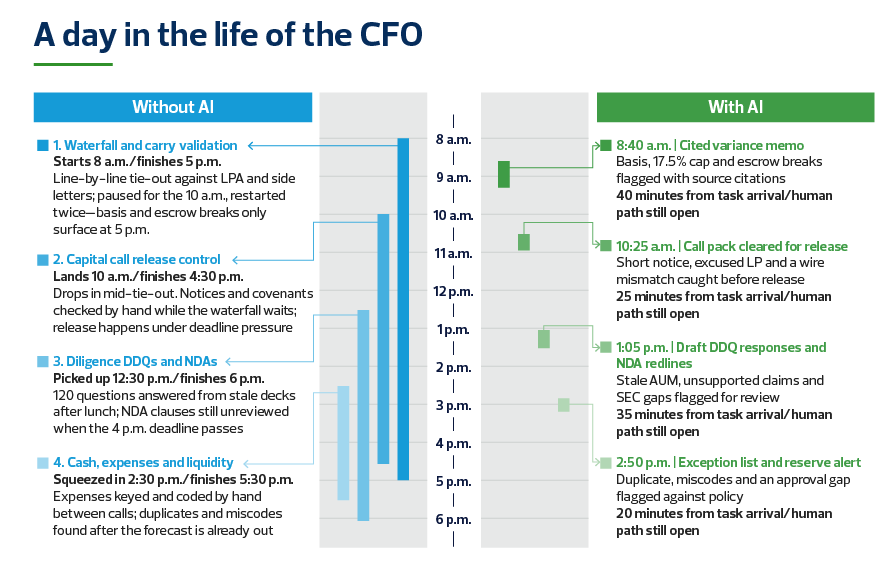
Here are four illustrative examples of how AI-enabled CFOs can shift routine work toward exception-based review and better decisions. Results will vary based on data quality, process complexity, technology integration, governance and the level of human review required.
1. Reviewing and validating waterfall models
Quarter-end close culminates with the waterfall calculation. Long formulas, version questions and eight- to 16-hour turnaround cycles can limit the process to one or two iterations when analysis matters most.
In a governed environment, AI can organize fund terms, source data and calculation logic; compare model provisions with governing documents; and surface assumptions or inconsistencies requiring review. The CFO can shift time from mechanical review toward scenario analysis, allocation implications and judgmental review. Here is an example starter prompt to reduce waterfall review time:
Act as a private fund finance analyst supporting quarter-end close.
Using the attached LPA, side letters and waterfall excel workbook, validate the waterfall model.
Your objective is to help the CFO understand:
- Summarize the distribution waterfall structure
- Identify key assumptions, hurdles, catch-up provisions, carried interest mechanics and allocation rules
- Compare model logic to governing document requirements
- Flag inconsistencies, missing inputs, unsupported calculations or provisions that may require human interpretation
- Identify assumptions that could materially change allocation outcomes
Output format:
- Waterfall summary
- Critical assumptions
- Potential discrepancies
- Items requiring CFO review
- Relevant LPA citations by section
Use exception-focused language. Don’t modify calculations. Focus on validation, transparency and items needing human judgment.
2. Executing capital calls and distributions with greater control
Capital events are visible to LPs but can be fragmented internally. Even when an administrator performs key steps, the CFO remains responsible for oversight, timing, communications and exception escalation.
In an integrated, governed workflow, AI can assemble documents and data, identify inconsistencies, support allocation review, prepare draft notices and route defined approval steps. The accounting and investor relations teams still validate calculations, exceptions and messaging. The CFO no longer reconciles versions or waits for status updates; attention shifts to draw timing, liquidity implications, unresolved exceptions and communication quality. Here is an example starter prompt to strengthen capital-event control:
Act as a fund operations reviewer supporting a capital event.
Using the draft capital call or distribution notice, compare it against the attached notice template, LPA, side letters and investor records.
Your tasks are to:
- Validate investor-specific requirements
- Identify inconsistencies across documents
- Flag allocation, timing or approval issues
- Highlight missing information that may impact the event
- Identify items requiring legal, controller or CFO review
Output format:
- Executive summary
- Exceptions identified
- Investors affected
- Required approvals
- Recommended actions prior to release
Use concise, release-readiness language. Provide source references for each finding and do not approve the event.
3. Turning DDQs and NDAs into an exception-based review
A 120-question due diligence questionnaire (DDQ) can send investor relations, finance, legal, compliance and IT searching through prior responses, policies and data rooms. Reusing old answers creates risks from outdated metrics, inconsistent disclosures or unsupported claims.
For DDQs, AI can classify questions, retrieve approved language, map responses to sources and flag stale or unsupported content. For nondisclosure agreements (NDAs), AI can summarize deviations from approved positions and route issues to legal reviewers. Subject matter experts remain responsible for validation, legal reviewers for legal judgment, and the CFO for sensitive disclosures.
The difference is that the CFO reviews true exceptions instead of managing a document scavenger hunt. Here is an example starter prompt to turn diligence into an exception review:
Act as a diligence review analyst.
Using the attached DDQ responses and approved response library, perform an exception review.
Your tasks are to:
- Identify responses that match approved language
- Flag stale information, unsupported claims and inconsistent disclosures
- Highlight questions requiring legal, compliance, IT, finance or investor-relations review
- Identify areas where supporting documentation is unavailable
- Summarize material deviations from standard firm language
Output format:
- Summary of review
- Responses requiring updates
- Unsupported assertions
- Legal/compliance exceptions
- Recommended actions
Use audit-ready language. Cite the source supporting each response and issue, and separate confirmed exceptions from items needing review.
4. Managing cash and expenses by exception
Daily cash and expense management is fragmented and error-prone, creating risks around duplicate payments, coding errors and liquidity.
AI can extract invoice data, compare coding against policy and prior treatment, match bank movements to approved payments, and flag missing approvals or unusual activity. Prior treatment can inform review, but should not override current policy or judgment.
CFO’s time moves from validating routine transactions to resolving judgmental allocations and testing liquidity choices. An example starter prompt to manage cash and expenses by exception:
Act as a fund finance reviewer for liquidity and expense controls.
Using the attached invoices, coding details, payment records and expense policies, perform an exception review. Use only the materials provided.
Your tasks are to:
- Compare coding treatment against policy and prior practice
- Identify duplicate payments, allocation concerns, missing approvals or unusual transactions
- Highlight transactions that may affect liquidity, covenants or fund reserves
- Distinguish confirmed discrepancies from potential issues requiring investigation; flag items requiring judgment or escalation
- Summarize significant risks requiring management attention and cite the applicable source and section for each finding
Output format:
- Executive summary
- Control exceptions
- Liquidity considerations
- Approval issues
- Recommended actions
Use concise, CFO-ready language. Do not make or approve accounting, legal, tax, allocation or payment decisions. Clearly separate confirmed exceptions from observations requiring further investigation.
Impact of AI-enabled execution
By building fluency with AI prompting and applying it to routine tasks, CFOs can reshape their calendars around exceptions, judgement and decisions that create value. They can standardize effective practices across the team and engage technology providers and partners from a stronger understanding of where deeper automation belongs.
The objective is not to automate judgment or remove CFOs from the process. It is to focus CFOs’ attention where it creates most value: interpreting exceptions, challenging assumptions, validating governance, assessing risk and guiding consequential decisions that require human expertise.
RSM contributors
Related insights
FUND ADMINISTRATION DONE DIFFERENTLY
Integrated services to achieve operational alpha